

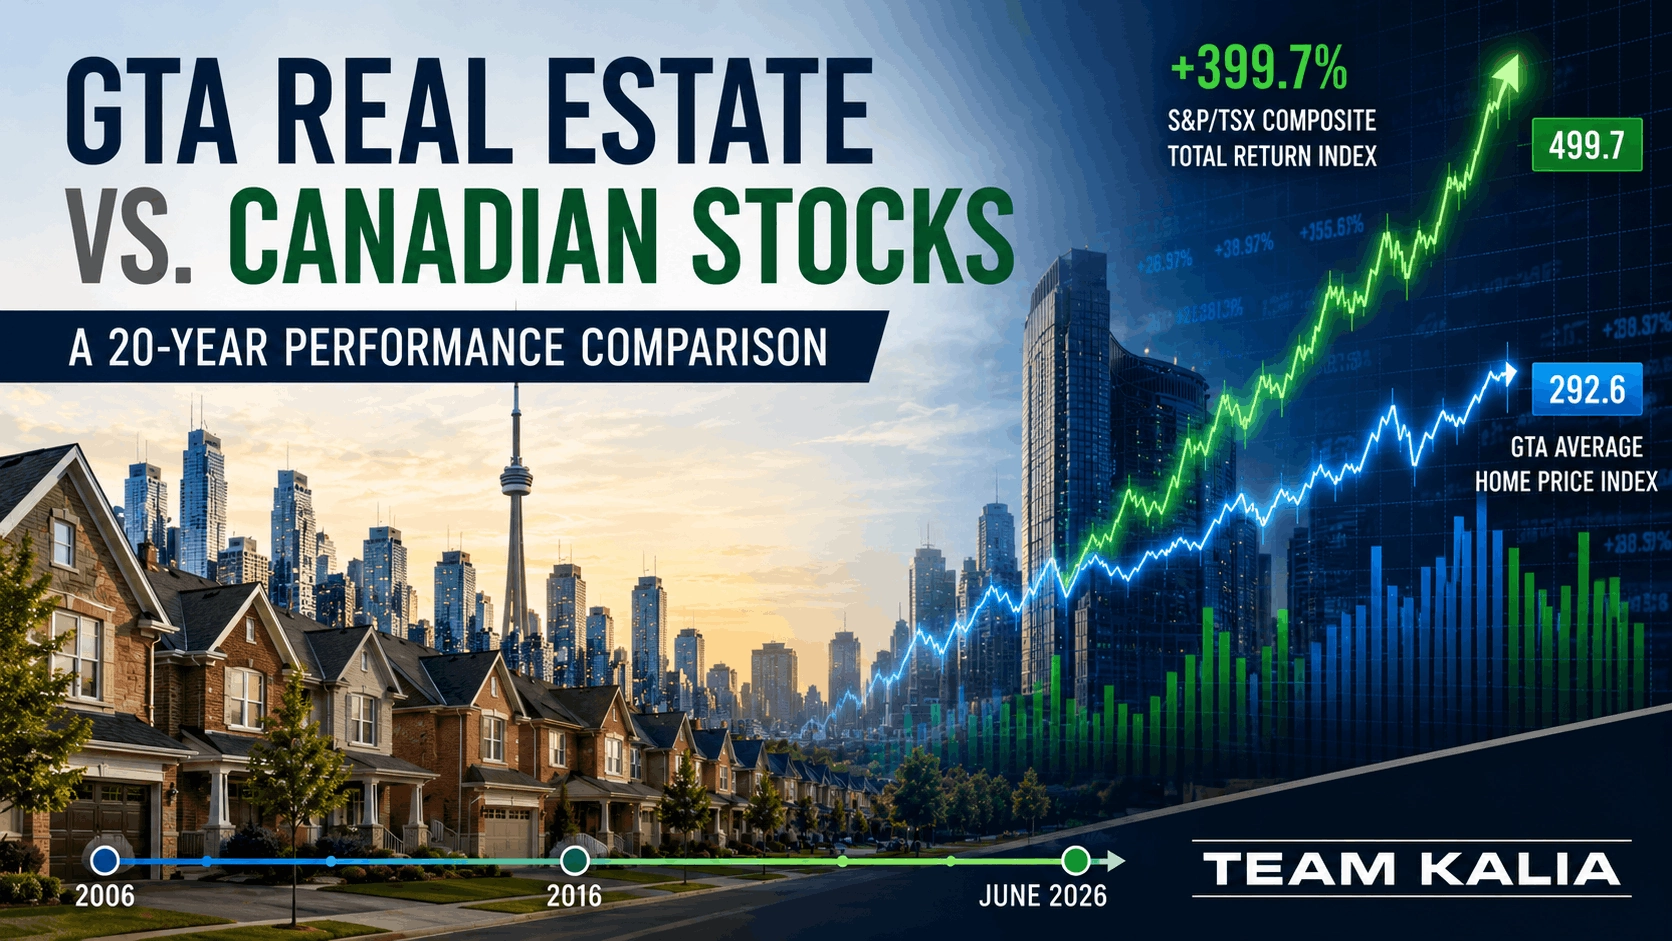
GTA Real Estate vs. Canadian Stocks: A 20-Year Performance Comparison
Two Decades of Data, Practical Insights, and Lessons for Today’s Homebuyers and Investors
How did GTA residential real estate perform compared with the Canadian stock market over the past 20 years and what can this history teach today’s homebuyers and real estate investors?
Few investment debates generate stronger opinions than real estate versus stocks. Some people believe owning property is the surest path to wealth, while others argue that a diversified stock portfolio has historically produced superior long-term returns.
There is no universal answer. Stocks and real estate work very differently, serve different purposes and carry different risks.
Stocks offer liquidity, diversification and the ability to invest gradually. Real estate may provide shelter, rental income, responsible leverage and the gradual accumulation of equity through mortgage repayment.
In this article, I compare the performance of GTA residential real estate with the Canadian stock market from 2006 through June 2026. I also examine what the comparison leaves out and why current GTA market conditions may deserve the attention of financially prepared homebuyers and long-term real estate investors.
The purpose of this comparison is not to declare one investment the permanent winner. It is to understand how both markets performed, why their results differ and what those results may mean for investors today.
Key Takeaways
- Canadian stocks outperformed GTA average home prices during the period examined.
- The stock-market comparison includes reinvested dividends, while the housing comparison does not include leverage, rental income or mortgage-principal repayment.
- Real estate also carries substantial ownership, financing and transaction costs that are not reflected in the chart.
- GTA buyers generally have more choice and negotiating power than they had near the beginning of 2022.
- No one can reliably identify the exact bottom of a housing or stock-market cycle.
- Financial readiness, property quality and the ability to hold for the long term are usually more important than perfectly timing the market.
Executive Summary
If you only have a few minutes, here is the essence of this article:
- Canadian stocks delivered stronger long-term returns than GTA average home prices between 2006 and June 2026.
- The comparison does not include several important advantages of real estate, including mortgage leverage, rental income and mortgage-principal repayment.
- Today’s GTA buyers generally have greater negotiating power than they did near the market peak.
- No one can reliably identify the exact bottom of a housing cycle.
- Long-term success depends more on buying wisely, maintaining affordable payments and holding quality assets than on perfectly timing the market.
Table of Contents
- The 20-Year Comparison Chart
- What the Results Show
- Why This Is Not a Perfect Comparison
- How Leverage Changes the Real Estate Calculation
- Why Starting and Ending Dates Matter
- GTA Home Prices Since the February 2022 Peak
- What Has Changed in the GTA Market?
- Prices Below Earlier Market Peaks
- Are There Early Signs That the Housing Correction Is Stabilizing?
- Could This Be a Good Time to Buy?
- What Real Estate Investors Should Consider
- You Do Not Need to Buy at the Exact Bottom
- Why Real Estate and Stocks Can Work Together
- Final Thoughts
GTA Real Estate vs. Canadian Stocks: The 20-Year Chart
The following chart compares two broad Canadian market measures:
- GTA residential real estate: Toronto Regional Real Estate Board average selling prices
- Canadian stocks: S&P/TSX Composite Net Total Return Index
Both series are indexed to 100 using their respective 2006 averages. Indexing allows us to compare percentage growth even though the original home-price and stock-index values were different.
For example, a value of 200 means that the measure has doubled from its starting level. A value of 300 means that it has tripled.

Both series are indexed to 100 using their respective 2006 averages.
Download the Supporting Excel Workbook
Methodology Note: The stock-market performance shown in this comparison is based on the S&P/TSX Composite Net Total Return Index, which assumes that dividends are reinvested. The real estate comparison reflects changes in the TRREB GTA Average Home Price only and does not include rental income, mortgage-principal repayment, leverage, ownership costs, transaction costs or tax considerations. As a result, the comparison focuses on long-term market performance rather than the total investment return an individual investor may achieve.
What the Comparison Shows
Using the 2006 averages as the starting point, the GTA average home-price series increased from 100 to approximately 292.6 by June 2026. This represents total growth of approximately 192.6%.
The S&P/TSX Composite Net Total Return series increased from 100 to approximately 499.7. This represents total growth of approximately 399.7%.
The approximate annualized growth rates during the period were:
- GTA average home prices: approximately 5.5% per year
- Canadian stocks, including reinvested dividends: approximately 8.4% per year
On the surface, this appears to be a clear victory for Canadian stocks. However, the comparison becomes much more nuanced once leverage, rental income, ownership costs and mortgage-principal repayment are considered.
Based strictly on these two market measures, Canadian stocks produced the stronger return between 2006 and June 2026.
This result may surprise people who remember the extraordinary rise in GTA home prices during the years leading up to early 2022.
However, the Canadian stock-market measure benefited from approximately two decades of business growth, capital appreciation and reinvested dividends. GTA real estate also experienced a meaningful correction following its earlier market peak.
The result does not mean that every stock investor earned more than every real estate investor. Nor does it prove that stocks will outperform real estate during the next 20 years.
It simply tells us what happened between the selected starting and ending points using the specific measures included in the analysis.
Why This Is Not a Perfect Apples-to-Apples Comparison
A chart can compare market performance, but it cannot capture every benefit, expense, tax consequence and personal circumstance affecting an individual investor.
The Stock-Market Result Includes Reinvested Dividends
The S&P/TSX Composite Net Total Return Index reflects both changes in stock prices and the reinvestment of dividends after the applicable index-level withholding-tax adjustment.
This is important because Canadian companies, particularly banks, utilities, telecommunications companies, pipelines and other established businesses, have historically paid meaningful dividends.
When dividends are reinvested, they purchase additional shares. Those additional shares may then generate their own future dividends and capital growth. This compounding can make a substantial difference over a period of 20 years.
The comparison does not deduct investment-management fees, ETF expenses, mutual-fund fees, trading commissions or personal income taxes. The return actually received by an investor may therefore differ from the index return.
The Housing Result Measures Price Growth Only
The real estate line reflects changes in GTA average selling prices. It does not calculate the complete return earned by an individual homeowner or landlord.
It excludes:
- Mortgage leverage
- Rental income
- Mortgage-principal repayment
- The value of living in a principal residence
- Renovations and property improvements
- Individual property performance
Real estate is also not a standardized investment. Two properties purchased for the same price can produce very different results because of their location, lot size, condition, layout, property type and neighbourhood demand.
Average Price Is Not the Same as a Repeat-Sales Index
The GTA average selling price is affected by the mix of properties sold during a particular period.
For example, if an unusually large percentage of detached luxury homes sells in one month, the average price may rise even if the value of a typical home has not increased by the same amount. If more condominiums and lower-priced homes sell, the average may decline.
Despite this limitation, average selling prices remain useful for a broad, understandable comparison, particularly when examined over a long period rather than focusing on one month.
The chart shows how two broad market measures changed. It does not calculate the exact after-expense return of a particular homeowner, landlord or stock investor.
How Leverage Changes the Real Estate Calculation
Most people do not buy a home or investment property entirely with cash. They contribute a down payment and finance the balance with a mortgage.
This means that a buyer may control an asset worth considerably more than the original amount invested.
A Simplified Example
Suppose an investor purchases a $1,000,000 property with a $200,000 down payment and finances the remaining $800,000.
If the property increases in value by 5%, it is now worth $1,050,000. The property itself appreciated by $50,000, or 5%.
However, the $50,000 increase is equal to 25% of the original $200,000 down payment.
This is the potential power of responsible leverage. The investor benefits from appreciation on the entire property, not only on the cash used for the down payment.
Leverage Works in Both Directions
The calculation becomes much less attractive when prices decline.
If the same $1,000,000 property falls by 10%, its value declines by $100,000. That decline equals half of the investor’s original $200,000 down payment, before considering transaction costs.
Leverage can therefore magnify both gains and losses.
A highly leveraged buyer may also face difficulty if:
- Mortgage rates rise at renewal
- Rental income is interrupted
- Major repairs become necessary
- Employment or business income declines
- The property must be sold during a weak market
Leverage is not automatically good or bad. Its usefulness depends on the purchase price, financing terms, income stability, cash reserves and ability to hold the property through market fluctuations.
Rental Income and Mortgage Repayment Also Matter
An investment property may produce returns in three main ways:
- Property appreciation
- Rental income
- Mortgage-principal repayment
Even when a property’s market value is temporarily unchanged, a portion of each mortgage payment may reduce the outstanding loan balance. Over time, this can increase the owner’s equity.
A tenant may also contribute toward the property’s mortgage, taxes and other expenses through monthly rent.
However, gross rent should never be mistaken for profit. A proper analysis must account for the complete cost of ownership.
Real Estate Has Significant Carrying and Transaction Costs
The benefits of leverage, rental income and mortgage repayment must be considered alongside the costs of owning and selling real estate.
Depending on the property, these may include:
- Mortgage interest
- Property taxes
- Home insurance
- Repairs and regular maintenance
- Condominium fees
- Utilities paid by the owner
- Vacancies and missed rent
- Property-management expenses
- Renovations and major capital expenditures
- Provincial and municipal land transfer taxes
- Legal fees
- Appraisal and financing expenses
- Real estate commission and selling costs
- Applicable income and capital-gains taxes
A homeowner also receives the practical benefit of having a place to live. That benefit has real value because the owner would otherwise have to rent another home. However, it is difficult to represent fairly in a simple market-performance chart.
Why the Starting and Ending Dates Matter
Investment comparisons can change considerably depending on the selected starting and ending dates.
The Canadian stock market experienced a major decline during the 2008–2009 Global Financial Crisis. An investor measuring returns near the bottom of that decline would have reached a very different conclusion than someone evaluating the market several years later.
Similarly, GTA real estate experienced exceptional appreciation throughout much of the following decade. Low borrowing costs, strong population growth, constrained housing supply, and intense buyer competition all contributed to rapidly rising home prices.
Home prices reached historically high levels in early 2022 after the Bank of Canada reduced its policy interest rate to near historic lows during the COVID-19 pandemic to support the economy. Exceptionally low borrowing costs, combined with strong demand and limited housing supply, fuelled one of the strongest housing booms in recent history. As inflation accelerated, the Bank of Canada began raising interest rates sharply in 2022, reducing affordability and leading to a significant market correction.
Had this comparison ended near the market peak in early 2022, the results would have appeared much more favourable to GTA real estate. Ending the analysis in June 2026, after the subsequent correction, produces a considerably stronger outcome for Canadian stocks.
Neither observation is necessarily wrong. Instead, it demonstrates how strongly long-term comparisons can be influenced by the choice of measurement period.
Historical results are factual, but the conclusions we draw from them can change depending on where we begin and end the comparison.
GTA Home Prices Since the February 2022 Market Peak
The long-term comparison above uses annual average home prices so that GTA real estate and Canadian stocks can be measured consistently over a 20-year period. Annual averages are useful for studying long-term performance, but they smooth out the exceptionally high monthly prices reached during the early-2022 housing market frenzy.
The chart below shifts the focus exclusively to the GTA housing market. It tracks the monthly TRREB GTA average selling price from the February 2022 market peak through June 2026.

Monthly TRREB average selling prices, shown to the exact dollar in the accompanying database, reveal the depth and path of the housing correction more clearly than annual averages.
Download the CondoPundit GTA Housing Database
Key result: The GTA average selling price declined from $1,334,544 in February 2022 to $1,058,658 in June 2026—a precise decline of 20.7%.
This monthly measure is much closer to what many homeowners and real estate professionals have experienced when comparing current sales with the strongest prices achieved in early 2022. In a number of neighbourhoods and property segments, peak-to-current declines of approximately 20% to 25%, and sometimes more, may be observed through a careful comparative market analysis.
Like any market-wide average, the GTA average selling price should still be interpreted carefully. It can move because property values change, but it can also be affected by the mix of homes sold. For example, a month with proportionately more detached-home sales and fewer condominium sales may produce a higher average price even when values within both categories remain under pressure.
The annual chart shows the long-term investment picture. The monthly chart shows the depth and path of the housing correction since the 2022 peak. Both are accurate because they measure different aspects of the market.
What Has Changed in the GTA Real Estate Market?
The monthly chart helps explain why today’s GTA market feels so different from the highly competitive conditions experienced near the beginning of 2022.
During the market peak, many buyers faced:
- Multiple competing offers
- Rapidly rising asking prices
- Short offer deadlines
- Pressure to submit unconditional offers
- Limited opportunity to inspect properties properly
- Fear of being permanently priced out
That environment shifted as financing costs increased and buyer demand weakened.
In many areas and price ranges, today’s buyers have:
- More properties from which to choose
- More time to compare homes and neighbourhoods
- A better opportunity to arrange a home inspection
- Greater ability to include financing conditions
- More negotiating power
- Less pressure to make an immediate decision
According to the Toronto Regional Real Estate Board, the GTA average selling price was $1,058,658 in June 2026, down 3.9% from June 2025. The MLS® Home Price Index Composite benchmark was down 5.4% year over year.
At the same time, June home sales increased compared with the previous year, suggesting that some buyers may be responding to lower prices, improved affordability and changing borrowing conditions.
These GTA-wide numbers should not be applied mechanically to every home. Conditions vary considerably by municipality, neighbourhood, property type, size, condition and price range.
Prices Remain Below Earlier Peaks in Many Market Segments
The monthly GTA average confirms a broad correction, but the experience of an individual homeowner depends on the specific property and neighbourhood. In many GTA communities, genuinely comparable properties are selling materially below the strongest prices achieved around the early-2022 market peak.
Based on broad market comparisons I have observed, the difference from earlier peak prices can sometimes be approximately:
- Detached homes: around $200,000
- Semi-detached homes: around $150,000
- Townhouses: approximately $100,000 to $150,000
- Condominium apartments: around $150,000
These figures are general observations, not formal valuations or predictions. The actual difference for a specific property may be much smaller or considerably larger.
A renovated home in a highly desirable school district may behave very differently from an outdated property on a busy street. A condominium with an exceptional view, practical layout and reasonable maintenance fees may outperform a nearby unit with less desirable characteristics.
Buyers should rely on recent sales of genuinely comparable properties rather than assuming that one GTA-wide percentage or dollar amount applies everywhere.
Borrowing Conditions Have Improved from Their Recent Highs
The Bank of Canada held its target for the overnight rate at 2.25% on July 15, 2026.
Mortgage rates remain higher than the exceptional pandemic-era lows, but borrowing conditions have improved from their recent peak. The actual rate offered to a borrower will depend on the lender, term, down payment, credit profile, income, property type and whether the mortgage is insured or uninsured.
Lower purchase prices and improved borrowing costs can work together to reduce monthly payments and the income required to qualify.
However, buyers should not base a purchase solely on the expectation of future rate cuts. The property should remain manageable under the mortgage terms available when the decision is made.
Are There Early Signs That the Housing Correction Is Stabilizing?
It is impossible to declare a housing-market bottom with certainty while it is happening. However, buyers and investors can watch for signs that market conditions are beginning to stabilize.
One potentially important signal is a sustained improvement in sales activity. Prices often receive the most attention, but the number of homes being purchased can begin recovering before prices show a clear upward trend.
Recent Canadian housing data have shown home sales increasing for several consecutive months while prices have begun to stabilize. This has led some economists and market observers to question whether the country’s prolonged housing correction may be approaching its later stages.
This does not mean that every Canadian housing market or every part of the GTA has reached its bottom. Real estate remains highly local, and conditions can differ substantially between provinces, municipalities, neighbourhoods and property types.
Why Sales Activity Can Change Before Prices
During a market slowdown, many potential buyers remain on the sidelines because they expect prices or mortgage rates to decline further. As affordability gradually improves and confidence begins returning, some of those buyers re-enter the market.
The first stage of a recovery may therefore appear as:
- More property showings
- A gradual increase in sales
- Fewer listings remaining unsold for extended periods
- More balanced negotiations between buyers and sellers
- Prices declining more slowly or beginning to level out
Only if demand continues to strengthen are home prices likely to resume a more consistent upward trend.
A housing recovery does not always begin with sharply rising prices. It may begin quietly, with more buyers making decisions and sales activity gradually improving.
Stabilization Is Not the Same as a Guaranteed Recovery
Early signs of improvement should be interpreted cautiously. Sales can strengthen temporarily, and economic conditions can change.
Historically, markets often recover gradually rather than all at once. Confidence usually returns after conditions have already begun improving, not before.
Employment, mortgage rates, population growth, consumer confidence and the supply of homes for sale will continue to influence the market. Some segments, particularly those with substantial inventory, may take longer to recover than others.
For buyers, the lesson is not that they must rush into the market. It is that waiting for universally positive headlines may mean waiting until a recovery is already clearly underway and some of today’s negotiating advantages have begun to disappear.
Could This Be a Good Time to Buy GTA Real Estate?
No one can reliably identify the exact bottom of a real estate cycle.
Prices could decline further, remain relatively flat or begin recovering sooner than expected. Employment, economic growth, housing supply, population changes, consumer confidence and borrowing costs will all influence what happens next.
Nevertheless, periods of weak sentiment can create opportunities for buyers who are financially prepared.
Who May Be in a Strong Position to Buy?
Current conditions may be worth considering for a buyer who has:
- Stable and sufficient income
- A suitable down payment
- Emergency savings remaining after closing
- The ability to manage the monthly payment comfortably
- A long-term ownership horizon
- A willingness to tolerate temporary price fluctuations
- A genuine housing or investment need
During a rapidly rising market, buyers may feel confident because prices are moving upward. However, they may also pay more, face intense competition and receive less favourable conditions.
During a slow market, buyers often feel nervous because headlines and public sentiment are negative. Yet they may gain more selection, more time and stronger negotiating power.
The best buying conditions can feel uncomfortable because confidence is often lowest when selection and negotiating power are greatest.
This does not mean that everyone should buy today. A purchase that creates financial stress is not made safe simply because prices have declined.
Who May Be Better Off Waiting?
Waiting may be prudent when:
- Employment or income is uncertain
- The down payment would use nearly all available savings
- Monthly carrying costs would be difficult to manage
- The buyer may need to relocate soon
- The buyer expects to sell again within the next three to five years
- High-interest consumer debt remains outstanding
- The purchase depends on immediate price appreciation
- The buyer is not comfortable with the responsibilities of ownership
The right market opportunity is only useful when it matches the buyer’s financial capacity and life circumstances.
What Long-Term Real Estate Investors Should Consider
An investment property should not be purchased solely because its asking price is below a previous market peak.
The property must also work as an investment.
Estimate the True Monthly Cost
A realistic analysis should include:
- Mortgage payment and interest cost
- Property taxes
- Insurance
- Condominium fees, where applicable
- Utilities paid by the landlord
- Repairs and maintenance
- Vacancy allowance
- Property-management costs
- Future renovations and major replacements
Investors should compare the complete monthly cost with realistic market rent, not an optimistic rental estimate required to make the numbers work.
Stress-test the investment. Consider whether the property would remain affordable if the mortgage rate were one or two percentage points higher at renewal, an unexpected repair became necessary or the property remained vacant for several months.
Examine the Quality of the Property
Long-term demand is usually stronger for properties that offer:
- Convenient access to employment and transportation
- Good schools and neighbourhood amenities
- A practical layout
- Suitable parking
- Reasonable ongoing expenses
- Features valued by future tenants and buyers
A lower price does not automatically make a property a good investment. Some properties are inexpensive because their location, condition or ongoing costs limit future demand.
Plan for Mortgage Renewal
An investor should consider whether the property will remain manageable if the mortgage renewal rate differs from the initial rate.
Using every available dollar for the down payment may leave the owner vulnerable when repairs, vacancies or higher payments arise.
Cash reserves are not idle money. They are part of the investment strategy.
Negative Cash Flow Requires Careful Thought
Some investors with high, stable incomes and substantial savings may accept a manageable period of negative cash flow when they believe the purchase price offers compelling long-term value.
However, the monthly shortfall should be calculated honestly and treated as an additional investment contribution.
A good property can become a poor investment if the owner is forced to sell during a weak market because carrying costs were underestimated.
You Do Not Need to Buy at the Exact Bottom
Market bottoms are usually recognized only after prices have already begun recovering.
Waiting for complete certainty may mean waiting until:
- Buyer confidence has returned
- Sales activity has increased
- Inventory has started declining
- Multiple offers have become more common
- Sellers have regained negotiating power
- Prices have already moved upward
A buyer does not necessarily need to purchase at the lowest price achieved during an entire market cycle.
Buying a suitable property at a reasonable price, maintaining affordable payments and owning it for many years may be far more important than identifying the perfect week or month.
A successful long-term purchase usually depends more on financial readiness, property quality and holding power than on perfectly predicting the market bottom.
Why Real Estate and Stocks Can Work Together
The stronger stock-market result in this comparison should not be interpreted as an argument against real estate. It should be understood as an argument for diversification.
Real Estate May Provide
- A place to live
- Responsible mortgage leverage
- Rental income
- Mortgage-principal repayment
- A tangible asset
- Potential long-term appreciation
Stocks, ETFs and Mutual Funds May Provide
- Liquidity
- Broad diversification
- Access to Canadian, U.S. and international businesses
- The ability to invest smaller amounts regularly
- Dividend and portfolio income
- Lower transaction costs
Real estate is concentrated. Even a valuable property remains one asset in one location and one market.
A diversified portfolio can hold hundreds or thousands of companies across different industries and countries. It can also be sold in smaller portions when cash is required.
On the other hand, stocks cannot provide a family with a home or allow an investor to use a conventional residential mortgage to control a substantial physical asset.
These investments do not have to compete for every dollar.
In my view, real estate and financial investments should not be viewed as competing choices. They can play complementary roles within a well-diversified long-term financial plan.
Readers interested in a broader discussion may also wish to read Real Estate vs. Stocks: Staying Diversified Is the Name of the Game.
Final Thoughts
Between 2006 and June 2026, both GTA real estate and Canadian stocks created substantial long-term growth.
Canadian stocks produced the stronger market return during this particular period. However, real estate offered benefits that the chart does not measure, including mortgage leverage, rental income, mortgage-principal repayment and personal use.
Real estate also involved substantial financing, maintenance and transaction costs that are not reflected in the home-price line.
The GTA housing market is currently below its previous peak in many neighbourhoods and property categories. Buyers generally have more selection and negotiating power than they had during the strongest period of the market.
No one can guarantee that prices have reached their lowest point. Markets may decline further, remain flat or begin recovering.
However, financially prepared buyers and investors with a long-term horizon may find that present conditions offer choices and negotiating opportunities that were unavailable near the market peak.
Real estate and stock markets move in cycles rather than straight lines. Strong periods are followed by slower periods, and difficult periods have historically given way to later recoveries, although the timing and strength of any future recovery cannot be guaranteed.
The objective should not be to predict every market turn. It should be to remain diversified, maintain adequate cash flow, avoid excessive debt and make decisions that can be carried comfortably through both strong and weak markets.
Wealth should eventually create security, freedom and choices. Investments are tools to help us build that life, not the final purpose of life itself.
For a broader reflection on this subject, read The Pursuit of Wealth and Happiness.
Related Reading
- Buying vs. Renting a Condo in Retirement — presents a detailed retirement case study comparing homeownership, investing and long-term estate value.
Sources and Methodology
GTA housing data: The housing comparison is based on Toronto Regional Real Estate Board annual average selling prices. The 2026 figure uses the sales-weighted average for January through June 2026. TRREB notes that historical figures may be revised when reporting methods or participating MLS® boards change.
Monthly housing chart and database: The second housing chart uses the exact monthly TRREB GTA average selling prices reported from February 2022 through June 2026. The accompanying CondoPundit GTA Housing Database preserves the figures to the dollar and is intended to illustrate the peak-to-current correction more clearly than the annual-average series.
Canadian stock-market data: The stock comparison uses the S&P/TSX Composite Net Total Return Index. Annual figures are based on monthly index averages, with January through June used for 2026. A net total return index reflects market-price movement and reinvested dividends after the index’s applicable withholding-tax adjustment.
Indexing: Both series are indexed to 100 using their respective 2006 averages. The indexed figures measure relative percentage growth and should not be interpreted as original prices or dollar investment balances.
Current market sources: Current GTA market statistics are drawn from the Toronto Regional Real Estate Board’s June 2026 market release. Information about the overnight policy rate is drawn from the Bank of Canada’s July 15, 2026 interest-rate announcement. Information about the Canadian equity index is based on the S&P/TSX Composite Index and its published methodology. The discussion of possible housing-market stabilization was also informed by the Financial Post article published through Yahoo Finance, “Canada’s Historic Housing Market Meltdown May Finally Have Hit Bottom.”
Author’s market observations: Approximate dollar differences from earlier peak prices are broad observations based on comparisons across GTA property categories. They are not formal market averages, individual property valuations or predictions of future prices.
I hope this comparison helps readers make more informed decisions, whether they choose real estate, stocks or a thoughtful combination of both.
Disclaimer
This article is provided for general educational purposes only and reflects the author’s personal observations as a real estate broker and long-term market observer. It is not financial, investment, mortgage, tax, accounting, legal or estate-planning advice.
Real estate values, investment returns, rents, expenses, mortgage rates, taxation and laws can change. Historical performance does not guarantee future results. The value and performance of an individual property may differ substantially from GTA-wide averages.
Readers should consult qualified real estate, mortgage, financial, tax and legal professionals before buying, selling, borrowing or investing.

